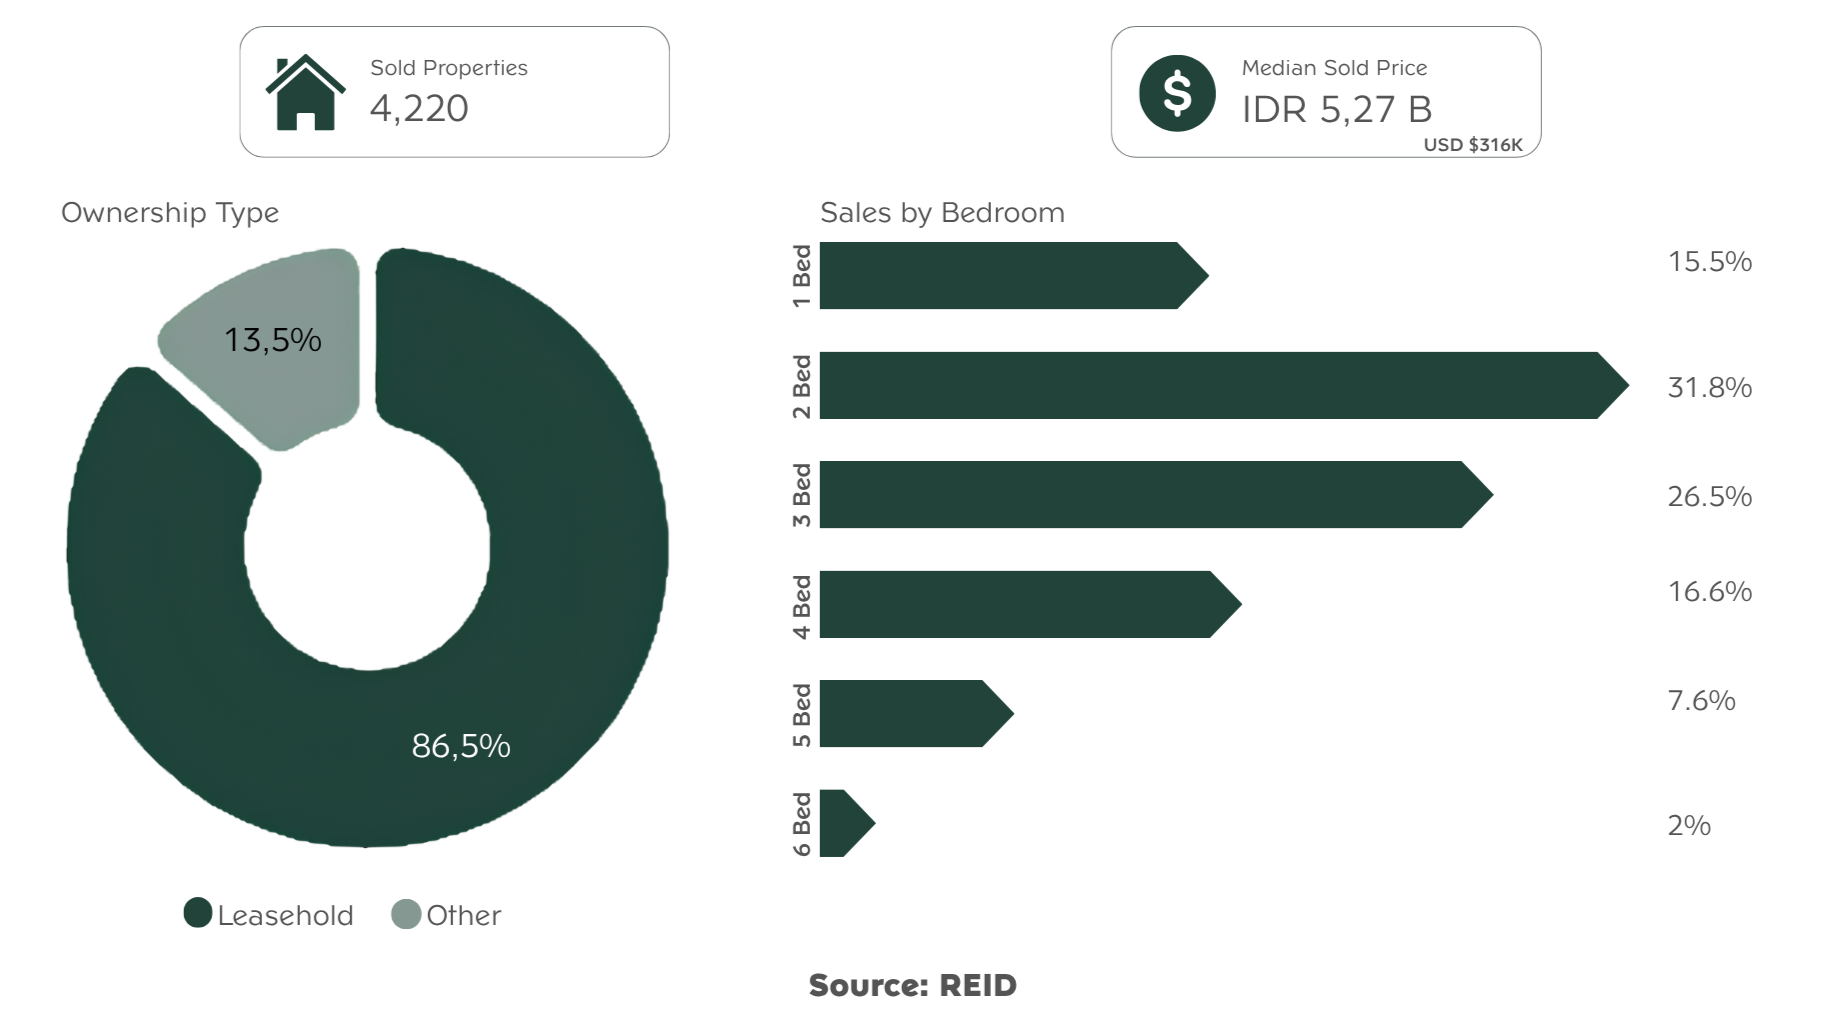
Bali's villa market reached the middle of 2026 showing clear signs of maturity rather than the rapid, volume-driven growth of prior years. According to Bali Home Immo's H1 2026 market review, REID recorded 4,220 villa sales over the 12 months ending in H1 2026, with transaction volume down 21% against the prior period, while median sold price rose 3.1% year-on-year to IDR 5.27 billion (~USD 316K).
Bali is no longer a market where simply owning a villa in a popular area is enough to justify the investment. Transaction activity has cooled, but pricing data suggests capital is becoming more selective rather than leaving the market altogether. Properties with stronger locations, practical layouts, rental potential, and clearer resale fundamentals are increasingly the ones attracting attention.
The investment case for Bali in 2026 is therefore becoming less about broad market momentum and more about asset selection. The opportunity is not simply "Bali property." It is finding the right property, in the right micro-market, at a price that still leaves room for income and future value.
Higher Revenue Does Not Always Mean Higher Yield
Rental revenue is important, but absolute income alone does not determine whether a property is a strong investment.
A villa generating IDR 600 million per year may initially appear more attractive than one producing IDR 450 million. However, if the first property requires substantially more capital to acquire and operate, its actual percentage return may be lower.
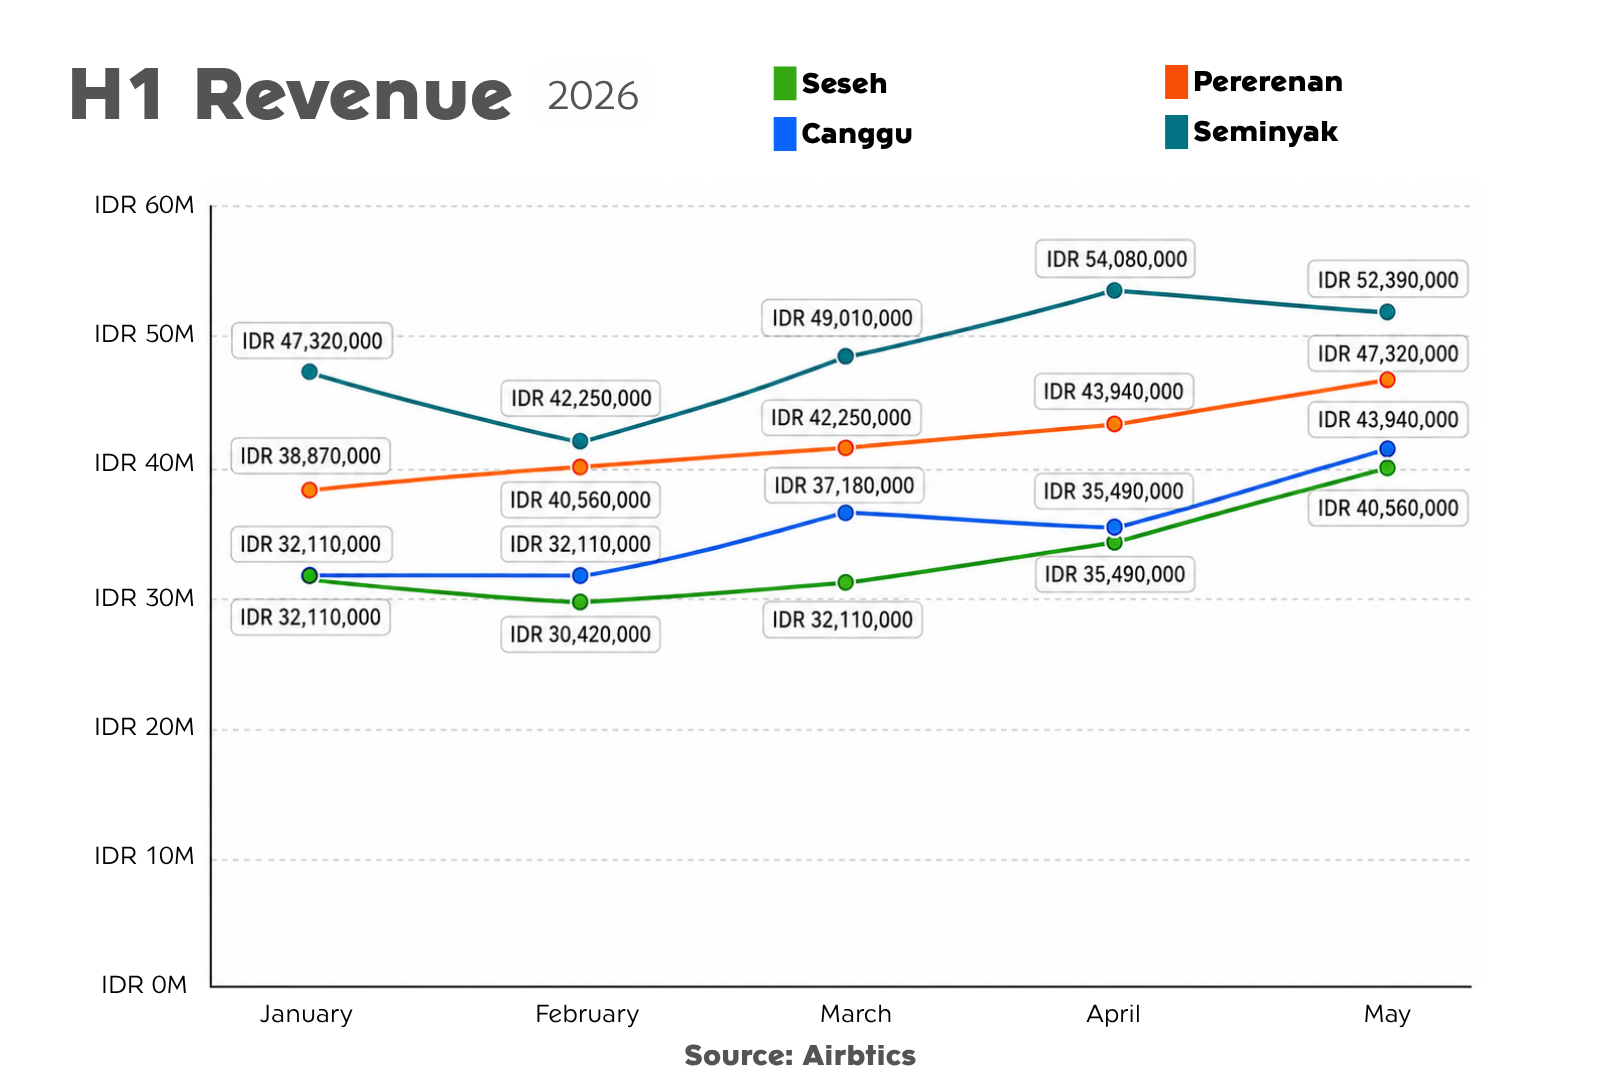
This underscores the value of deeper financial analysis to accurately assess the potential of a Bali investment. A high-grossing villa in a premium location may still offer a weaker return if the acquisition price has already absorbed most of the upside.
The distinction becomes especially important at neighbourhood level. A 2026 yield analysis of Berawa, Batu Bolong and Pererenan shows different performance patterns across areas within the same coastal market, and a similar pattern appears across Seminyak, where Beachside/Oberoi, Petitenget–Batu Belig and residential Seminyak offer different combinations of entry cost, ADR, occupancy and rental revenue.
For investors unfamiliar with Bali, this is one of the most important distinctions to understand: two villas marketed under the same broader destination can behave like completely different investments.
The strongest rental market is therefore not automatically the one producing the highest monthly income. The more useful measure is how much income a property generates relative to the capital required to acquire and operate it. A lower-priced villa with slightly lower revenue can produce a stronger percentage yield than a premium property generating higher gross income. In a more mature market, disciplined entry pricing becomes just as important as revenue potential.
Why 2026 Rental Figures Need Reading Carefully
One further reason to treat headline revenue with caution is what happened to rates this year.
Market-wide average daily rate fell 23% year-on-year to $125, while occupancy rose a relative 10% to 52% and total rental supply grew 5% to 44,750 properties. Total rental revenue declined 16% to $544 million.
Properties are filling more often but earning less per booking, as operators compete more aggressively for guests. Any income projection built on 2025 nightly rates will overstate what a villa realistically earns today, and that gap flows directly into any yield calculation resting on it.
Capital Growth: Where Returns Go Beyond Rental Income
Rental yield represents only one component of property investment performance. The second is capital growth: the increase in a property's market value over time.
The same REID data shows median villa prices increasing 3.1% year-on-year to IDR 5.27 billion, even while transaction volume declined by 21%.
This suggests a more selective market rather than uniform appreciation across every property category. Buyers may be completing fewer transactions, but stronger assets continue to attract demand and maintain pricing power.
That matters because investors should not rely on Bali-wide appreciation to compensate for a weak purchase. In a more mature market, capital growth is increasingly tied to the fundamentals of the individual property rather than the assumption that every villa will rise in value simply because it is located in Bali.
For investors, long-term capital growth is increasingly influenced by:
-
Location and surrounding infrastructure
-
Scarcity of comparable properties
-
Build and design quality
-
Property condition and maintenance
-
Rental performance
-
Demand within the property's price segment
-
Future development of the surrounding area
Properties that combine strong rental fundamentals with sustained buyer demand may therefore offer returns through both ongoing income and future resale value.
The stronger investment is not necessarily the property with the most aggressive appreciation forecast. It is the one with enough underlying market demand to remain attractive even if broader market growth slows.
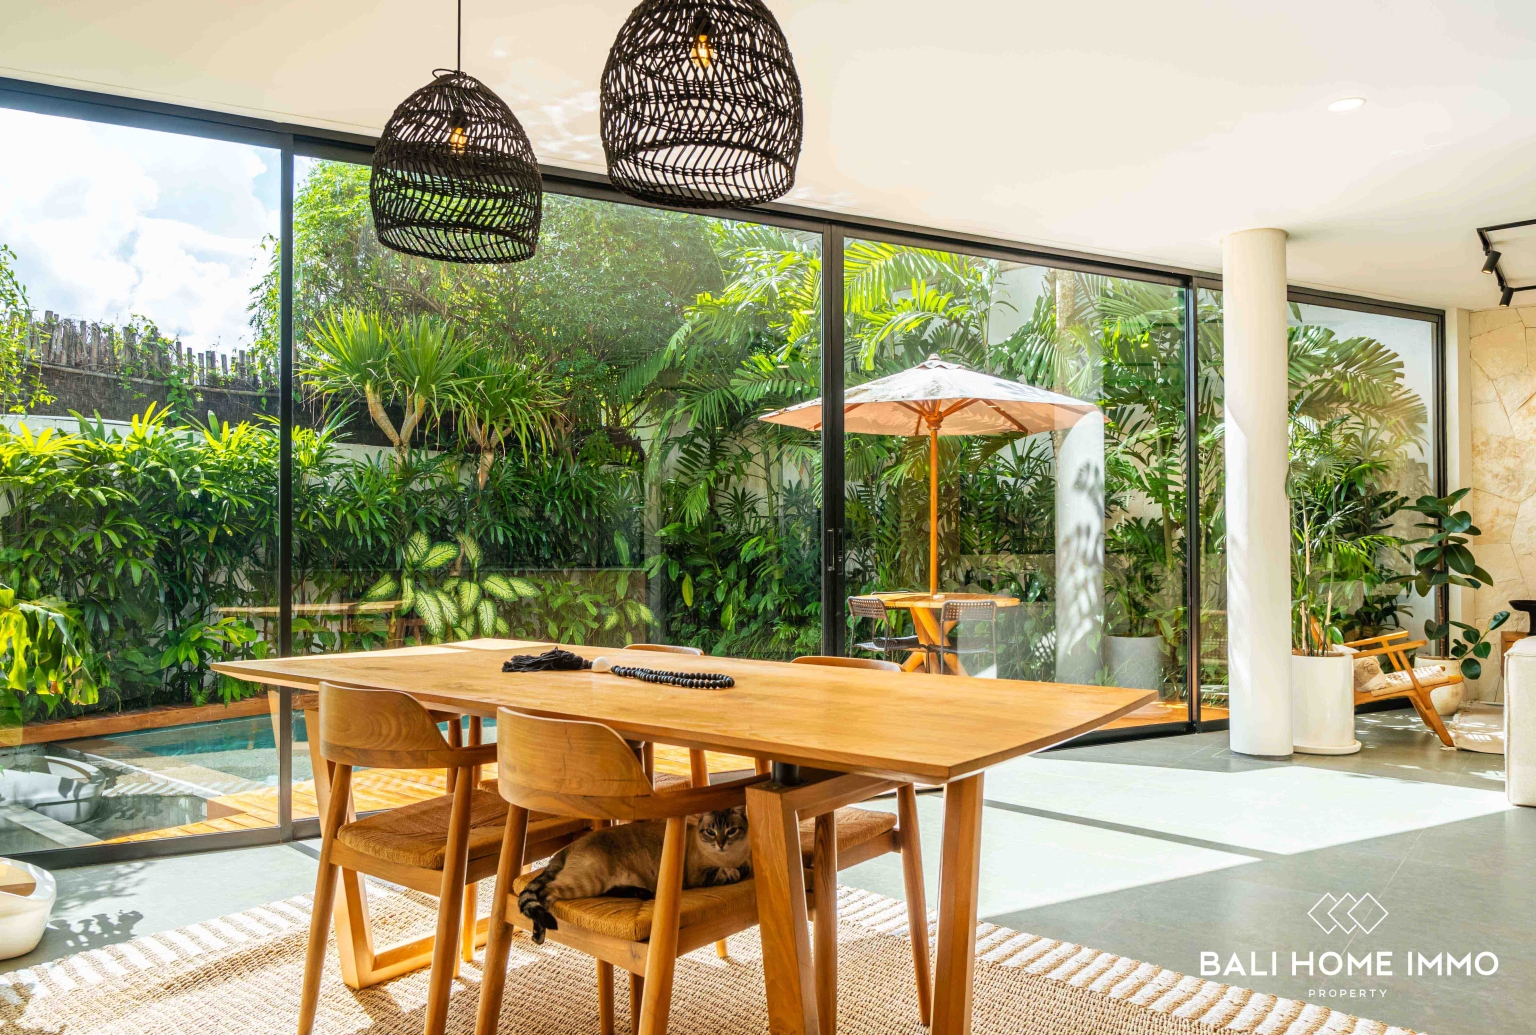
Why Two- and Three-Bedroom Villas Matter
Property configuration can influence both rental demand and resale liquidity.
According to REID's H1 2026 sales data, two-bedroom villas represented 31.8% of recorded sales, while three-bedroom villas accounted for 26.5%. Together they represented 58.3% of transactions, making the 2–3 bedroom segment the most actively traded part of the market.
Their appeal comes from flexibility. These properties can accommodate couples, families, groups, holiday guests and longer-stay tenants while generally requiring less capital and operating expenditure than larger estates.
For investors, this is not only a rental consideration. It is also an exit consideration. A property that serves a broader range of guests can also appeal to a wider pool of future buyers, supporting both rental performance and resale liquidity.
Larger or highly specialised villas can still produce strong results, but they may depend on a narrower guest profile and require more capital to acquire and operate. In a market where buyers are becoming more selective, flexibility can become a meaningful form of downside protection.
ROI Should Combine Income and Capital Growth
Investors often describe ROI only in terms of rental yield, but total property return can come from both rental income and property appreciation.
Looking at Total Investment Return
If a property generated a 4% net rental return during a year and its market value also increased by 3% over the same period, its total economic return would be around 7% before transaction costs and other investment-specific expenses.
That does not mean future appreciation is guaranteed.
However, evaluating both components provides a more complete picture than using rental yield alone.
A strong Bali investment should ideally be able to stand on two legs: operating income while the property is held, and enough underlying market demand to support value when the investor eventually exits.
A property producing slightly lower rental income today may still represent a strong investment if it is located in an area with improving infrastructure, limited comparable supply, or underlying market demand.
Conversely, an exceptionally high advertised rental yield may be less attractive if the property is difficult to resell or requires substantial ongoing expenditure.
This is also why headline ROI figures should be treated as the beginning of the analysis rather than the conclusion. A high projected yield means little if it depends on unrealistic occupancy, aggressive nightly rates, or a purchase price that leaves little room for future upside.
What Investors Should Evaluate Before Buying in 2026
As Bali's property market becomes more selective, investment performance increasingly depends on the relationship between purchase price, achievable rental income, operating costs, and future resale potential.
Investors should evaluate:
-
Purchase price versus rental revenue: higher income does not automatically mean higher ROI if the acquisition cost is disproportionately high
-
Net operating income: account for management, commissions, utilities, staffing, maintenance and vacancy
-
Occupancy and ADR assumptions: projections should be supported by realistic comparable properties rather than best-case scenarios, and by current rather than prior-year rates
-
Micro-location: properties within the same wider destination can have significantly different entry costs and rental performance
-
Property configuration and demand: practical layouts with a broad potential guest and buyer pool can support both rental and resale liquidity
-
Exit and capital-growth potential: consider infrastructure, scarcity, surrounding development and future buyer demand
The broader shift in 2026 is that Bali property investment is becoming increasingly performance-driven.
Buying in a famous destination alone is not enough. Investors need to understand how the purchase price relates to rental income, operating costs, market demand, and potential long-term capital growth.
Bali can still offer attractive investment opportunities, but the easy assumption that any well-located villa will perform is becoming harder to justify. The market increasingly rewards investors who treat the property as an operating asset rather than simply a lifestyle purchase.
The opportunity in 2026 is therefore not about buying quickly into a popular area. It is about buying an asset whose income, entry price, operating economics, and resale fundamentals still make sense when examined together.